You do not wake up and casually earn 100 credit score points because you manifested hard enough. You get them by fixing the stuff that is currently dragging your score around like a bad group project.
For US readers ages 18 to 25, this matters more than people admit because a better score can mean cheaper car insurance, easier apartment approvals, and fewer ugly surprises when you finally need a loan. The catch is that the internet loves impossible promises, while the real version is more boring and more useful.
The thing nobody actually says out loud
Raising your score by 100 points in 90 days is possible for some people, but not because of one secret trick. It usually happens when you combine a few fast moves: fix report errors, lower credit card utilization, and stop new damage from showing up.
That is not glamorous. It is also why most “fast credit repair” advice feels fake. Real score jumps usually come from cleaning up obvious problems, not from sprinkling credit fairy dust on your account.
The fastest score gains usually come from utilization, reporting errors, and avoiding new late payments.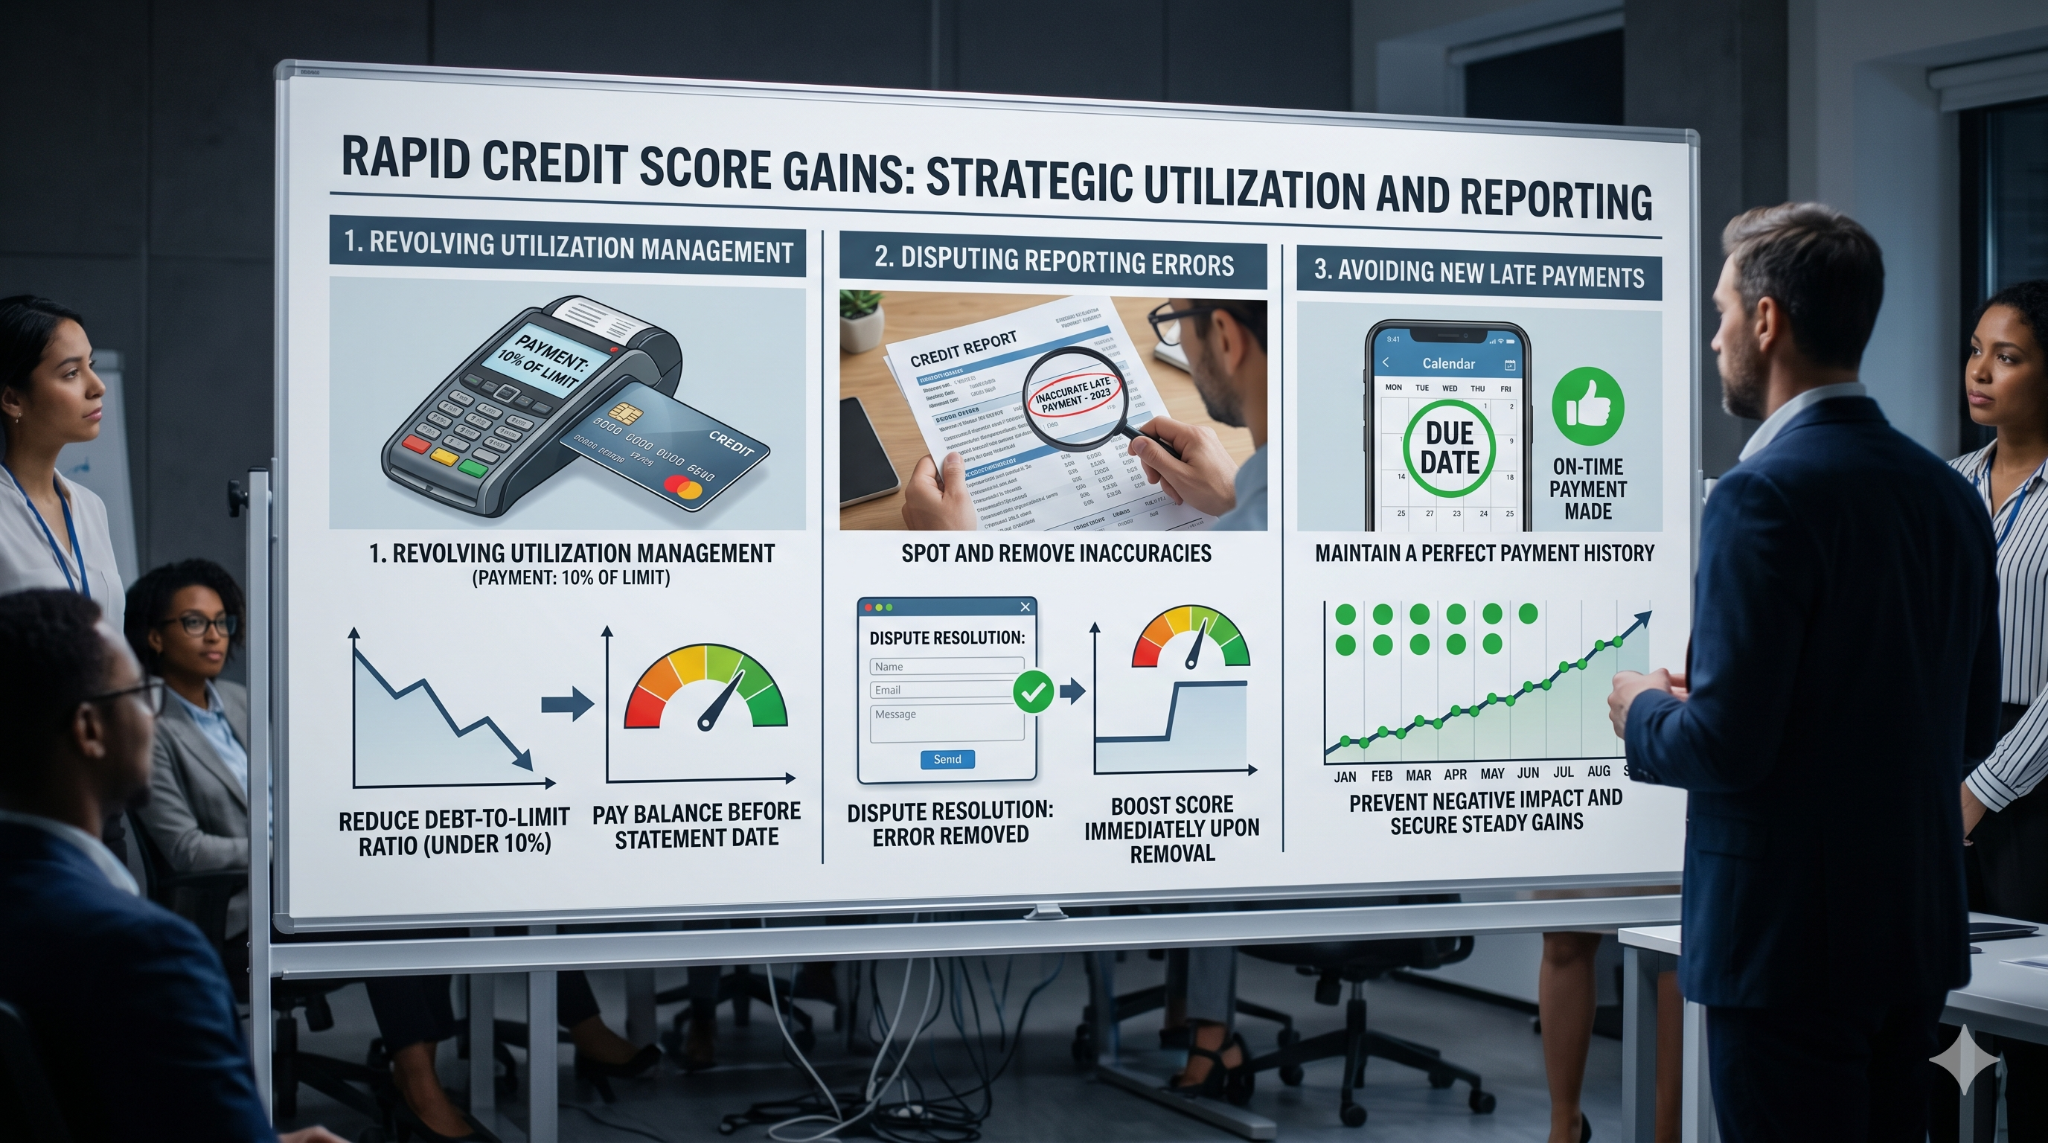
Payment history still matters most in FICO scoring, which is why one missed payment can hurt and one on-time streak can slowly pull you back up. FICO says payment history makes up about 35% of a FICO Score, so yes, the boring stuff is still the main event.
Credit scores are annoying because they reward calm behavior after chaos, not confidence after chaos.
How this actually works
A credit score is not a personality score. It is a risk model built from the way you use credit, and it reacts fastest to the parts that change quickly: balances, payments, and newly reported information.
The fastest lever for many people is credit utilization, which is the percent of your available revolving credit you are using. If your cards are near maxed out, your score can be dragged down hard. If you pay them down and keep balances low, the score can move faster than most other factors because the bureaus see the change quickly.
That is why a card balance dropping from ugly to reasonable can help more than opening five new accounts. The internet loves “building credit” content that sounds active and productive, but sometimes the move is just to stop carrying a giant balance around like a bad decision with interest.
Here is the part people miss:
- Lowering utilization can work fast because balances report monthly. If your card reports after payday instead of after your spending spree, that alone can change the number.
- A late payment hurts more than people expect. One late mark can stick around and make future progress feel slower until the damage fades.
- Disputing real errors can create sudden jumps. If a wrong late payment or incorrect account is removed, that is not “gaming” the system. That is fixing the file.
- Becoming an authorized user can help in some cases. But it only works if the primary cardholder has strong habits, because borrowed mess is still mess.
- New credit applications can be noisy. One inquiry is not a disaster, but five in a short window can make your profile look hungry and unstable.
- Payment consistency matters more than one heroic month. The score likes patterns, not dramatic speeches.
The daily-life comparison is simple. If your score is a GPA, utilization is the class you can fix this semester, while payment history is the class that took the whole year to repair. Both matter, but one moves faster.
Comparison
|
Option |
What it actually does |
Who it’s for |
The catch |
|---|---|---|---|
|
Pay down revolving balances |
Lowers utilization, which can improve scores quickly. |
Anyone with high credit card balances. |
The boost depends on when your lender reports the balance. |
|
Dispute errors |
Removes incorrect negative information from reports. |
People with wrong late payments, duplicate accounts, or identity mix-ups. |
Only real errors help; fake disputes waste time. |
|
Add an authorized user account |
May help if the primary account has strong history and low utilization. |
People with thin or damaged files who have a trusted helper. |
If the account is sloppy, you inherit sloppy. |
My take: if you want the biggest possible 90-day move, start with balances and errors before you bother with shiny “credit building” extras. The quick wins are usually boring, and the boring ones are the only ones that consistently show up in real files.
What actually happens when you try this
The first thing that surprises people is how fast the score can respond once a balance drops. You do not need a year for utilization changes to show up. In practice, the reported number can change on the next cycle, which is why a single payoff can feel weirdly powerful.
When you actually try this, the second surprise is how much of the “100-point” goal depends on what is wrong today. Someone with a wrong late payment or maxed-out cards may have a real chance at a huge jump. Someone with a clean file and already decent utilization may only get a smaller lift because there is less low-hanging fruit.
The thing that surprises people most is that the score often improves after they stop making credit “moves.” They open fewer accounts, pay on time, lower balances, and then wait. Boring wins here. Loud activity usually does not.
A pattern I keep seeing is that young adults think a credit score is mostly about having more accounts. That is only a tiny part of the picture. A clean payment record and low revolving balances usually matter much more than collecting cards like trading cards.
The advice everyone gives vs what actually works
“Just pay everything on time.” True, but incomplete. On-time payments help, yet if your cards are maxed out, your score may still be stuck because utilization is too high. The better move is autopay the minimums, then aggressively reduce balances on the highest-utilization cards.
“Open a new credit card to improve your mix.” That advice is often overrated for a 90-day sprint. A new account can add an inquiry and lower your average age, which can make the short-term picture messier. If you already have enough credit history, lowering balances is usually cleaner.
“Dispute everything.” No. Only dispute errors you can actually prove or reasonably challenge. If you fire off random disputes, you waste time and can miss the fixes that would have moved the score faster.
“Become an authorized user and you’re done.” Not even close. It can help, especially with thin files, but it is not a substitute for fixing your own utilization and payment record. Borrowed good habits help. Borrowed bad habits help too, which is the part nobody brags about.
The practical part
Pull all three credit reports first. Use the official free source and look for wrong late payments, accounts that are not yours, duplicate entries, and old negative items that should be gone. You cannot fix what you are guessing about.
Pay down revolving balances before the next statement closes. This matters because the reported balance is what the bureaus see, not your intention to pay later. If you only have one card carrying a high balance, that is usually your first target.
Set autopay for at least the minimum payment on every account. The CFPB has reported that autopay users are far less likely to fall 30 days past due, and avoiding new late marks is one of the easiest ways to stop score damage. One missed payment can wreck a lot of progress.
Ask for a credit limit increase only if you will not spend the extra room. A higher limit can lower utilization, but only if your spending stays controlled. If you treat the new limit like permission, you just recreated the problem with nicer branding.
Dispute one clean error at a time. Send documentation, keep copies, and track the result. If you are missing proof, do not guess your way into a dispute. That is not strategy. That is noise.
Avoid opening unnecessary new credit accounts during the 90 days. Each application can add friction, and a quick score plan works best when your profile is getting calmer, not busier.
Questions people actually ask
Also read:- Best Travel Credit Cards for Americans With No Annual Fee 2026
Can you really raise your credit score 100 points in 90 days?
Yes, sometimes. It is most realistic when your file has obvious problems like high utilization or reporting errors. If your file is already clean and stable, a 100-point jump is less likely because there is less to fix.
What is the fastest way to improve credit score?
For most people, lowering credit card utilization is the fastest visible change. Fixing errors can also help quickly if they are hurting your file. The main thing is to stop new late payments while the cleaner data catches up.
Does paying off a credit card help right away?
Usually yes, once the lower balance is reported to the bureaus. That is why timing matters so much. Paying the card down right after the statement closes is not as helpful as paying it down before the statement cuts.
Will one late payment ruin my score?
Not forever, but it can hurt a lot in the short term. Payment history is the biggest piece of a FICO score, so a late mark matters. The good news is that consistent on-time payments after the damage help rebuild the profile over time.
Should I close old credit cards?
Usually no, unless there is a specific reason like an annual fee you cannot justify. Closing cards can reduce your available credit and raise utilization, which can hurt the score you are trying to improve. Old, unused cards are often better left open.
Do credit limit increases help your score?
They can, if you do not spend more. A higher limit lowers your utilization ratio, which can help the score. But if the higher limit just becomes more spending room, the benefit disappears fast.
Is becoming an authorized user a good shortcut?
It can be, especially for a thin or younger credit file. The account only helps if the primary user has strong payment habits and low balances. If the account is messy, you are borrowing the mess too.
How often should I check my credit reports?
At least monthly if you are actively trying to improve your score. You do not need to obsess, but you do need to catch errors, new balances, or unexpected delinquencies fast. Waiting six months is how people miss the problem they were trying to solve.
So where does this leave you
If you want a real shot at 100 points in 90 days, the plan is not complicated. You need lower utilization, no new late payments, and a clean report with any real errors challenged fast. That is the whole engine. Everything else is accessories.
The part people hate is that the answer is both simple and slightly annoying. You cannot fake your way through this with a clever trick. You have to make the file look better.
One concrete thing to do today: pull your credit reports and write down your top two balances plus any errors you see. That gives you the first real move in the next 90 days, instead of another motivational rabbit hole.
Conclusion
You made it through the credit score version of adult homework, which is honestly more useful than half the self-help content on the internet. The good news is that scores do move. The less fun news is that they move for boring reasons.
If you remember one thing, keep this: fast credit improvement is usually a cleanup job, not a transformation story. Clean the file, cut the balance, stop the leaks. That is how the number changes.