You do not need “a lot” of life insurance just because some article said 10 times your income and then wandered off like that solved anything. You need enough to cover the people and bills that would still be there if you disappeared, which is less romantic than it sounds and more useful, too. For a 22-year-old in the US, that usually means thinking in terms of debts, income replacement, and whether anyone actually depends on your paycheck yet. The whole point is not to buy a scary number. It is to buy the right number, and not pay for nonsense you do not need.
The Thing Nobody Actually Says Out Loud
Most life insurance advice is written for a family with a mortgage, two kids, and a cable package they forgot to cancel. That is not most 18- to 25-year-olds. If you are young, the question is usually not “How do I protect my five dependents?” It is “What happens to my loans, my co-signer, my partner, or my parents if I die tomorrow?” That is a much smaller, sharper question, and weirdly, it is the one people avoid because it sounds too real.
Here is the part nobody likes to say: if nobody would suffer financially from your death, your need for life insurance may be low or even zero. That is not a moral judgment. It is math with feelings standing nearby. A lot of young adults buy coverage because they think adulthood means collecting financial products the way gamers collect side quests. It does not. You are not required to buy a policy just because you have a job and a toothbrush.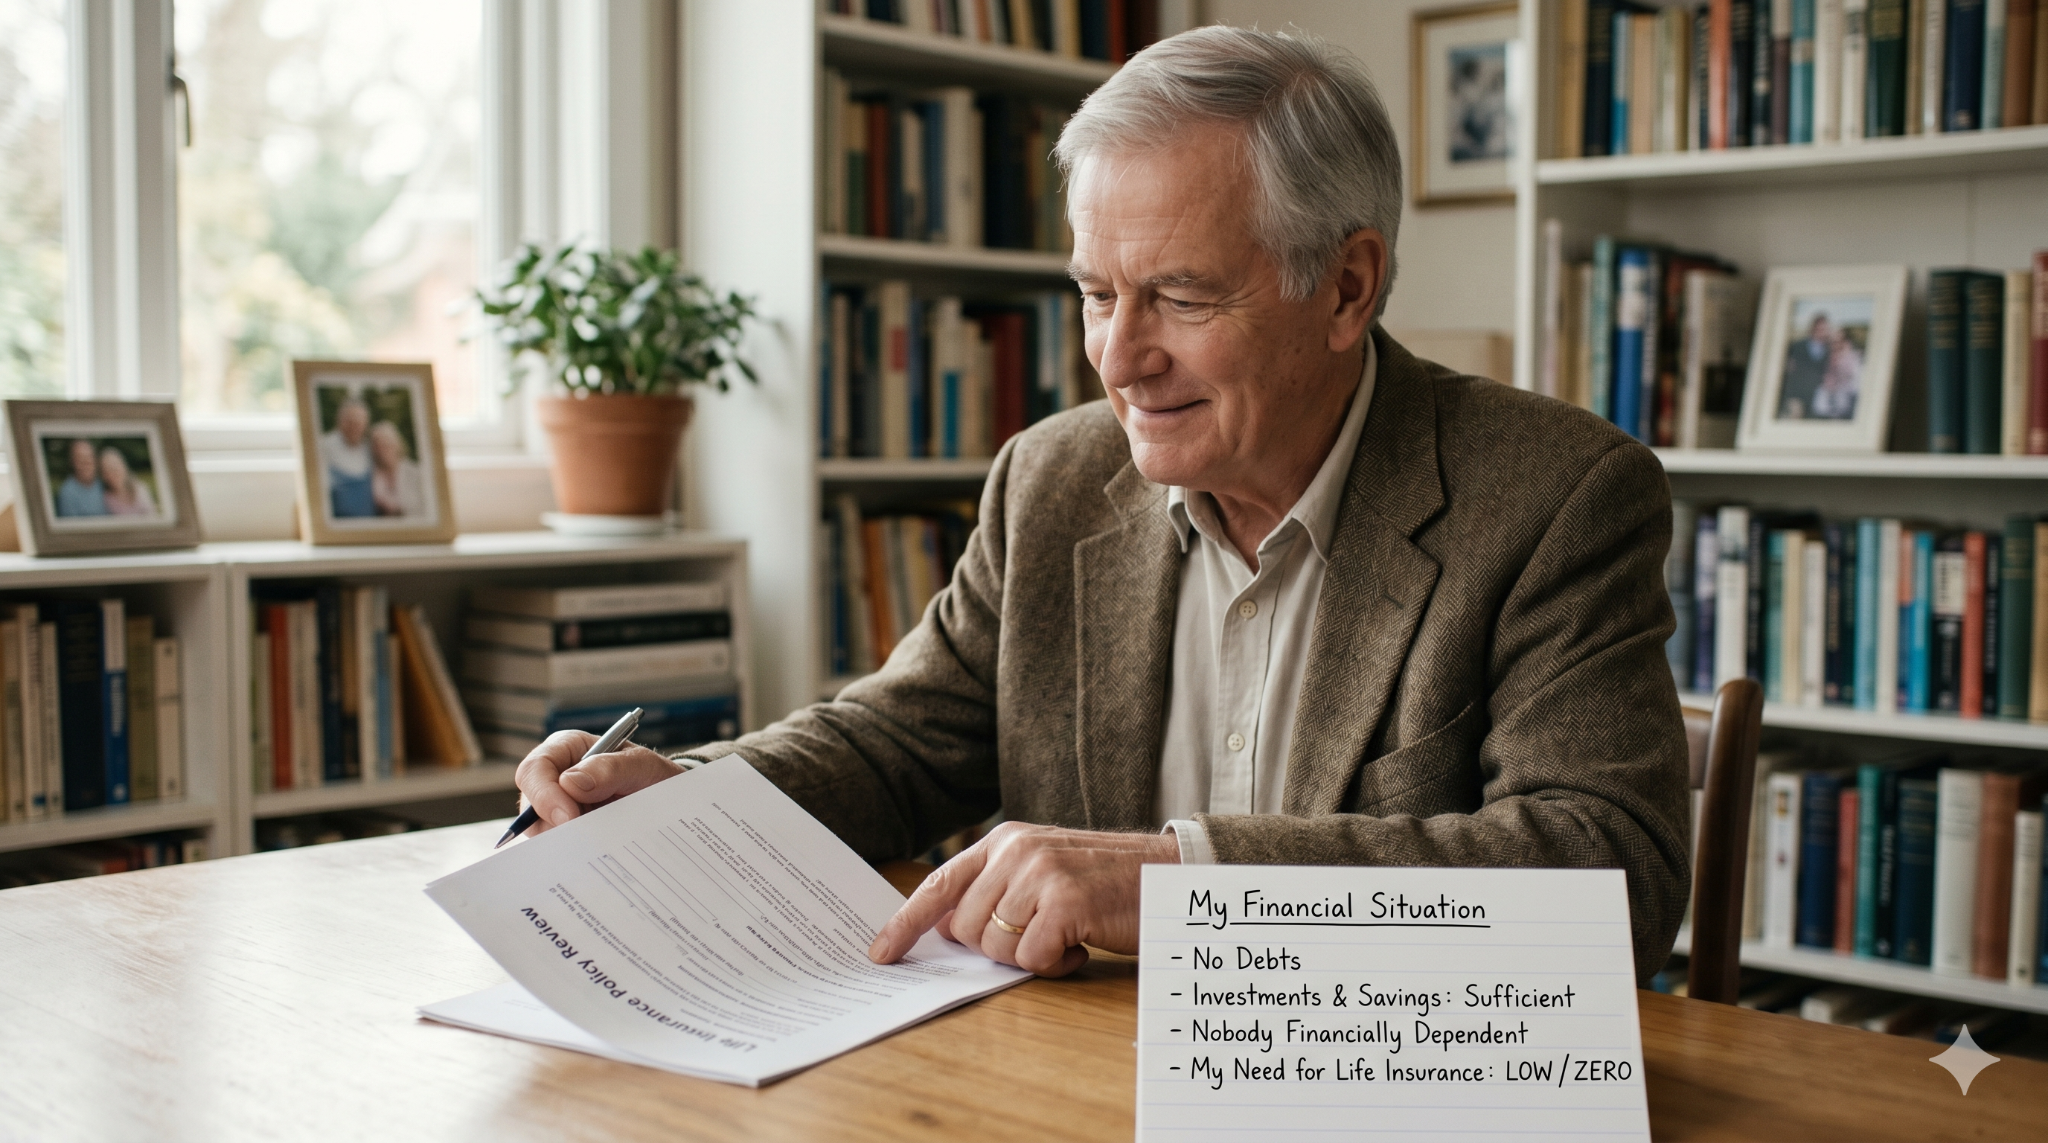
The useful way to think about it is simple. Start with who would be stuck with your bills, not who would be impressed by your planning. Student loans can matter, but in the US federal student loans are generally discharged when the borrower dies, while private loans depend on the contract and sometimes a co-signer gets left holding the bag. That is the kind of detail that changes the whole calculation. Same with rent, car loans, funeral costs, and whether your family would need help for a few months if your income vanished. The internet loves broad rules. Real life is annoyingly specific.
This is the part where people usually discover they were planning for a fantasy version of their own adulthood.
And yes, there is a reason the “10 times your income” rule keeps showing up. It is easy, memorable, and slightly too neat for real life. LIMRA and Life Happens have repeatedly shown a large coverage gap in the US, with many adults uninsured or underinsured. That does not mean every young adult needs a giant policy. It means lots of people are guessing instead of calculating.
How This Actually Works The Real Mechanics
The cleanest calculator method is not glamorous. It is the boring one that works. You add up what you would need covered, subtract what already exists, and stop pretending your vibes count as assets. That usually means debt, final expenses, income replacement, and any future costs you know are real, then minus savings and existing coverage. That is the whole machine.
For young adults, the major mistake is using a family-focused formula without the family part. If you are single, rent, and have no kids, you probably do not need a massive income replacement number. If you have a spouse, a child, a co-signer, or private student debt, the number changes fast. The point is not to buy protection for a scenario you do not have.
A practical way to run the math:
- Debt you would leave behind. Credit cards and car loans matter because they do not disappear just because your calendar got tragic.
- Private student loans with a co-signer. This is the sneaky one. Federal loans usually do not follow your family around after death, but private loans can.
- Funeral and end-of-life costs. Nobody wants to budget for this at 23, which is exactly why it belongs in the budget.
- Income replacement. If someone depends on your paycheck, estimate how many years they would need help.
- Existing savings and coverage. Emergency savings and workplace group life reduce how much extra you need.
- Future plans. If you have a child, a mortgage, or a partner who depends on you, the number rises fast.
A useful niche detail: for people in their early 20s, the decision is often less about “whole life vs term” and more about “do I need anything yet, and if yes, what is the smallest honest amount?” That is the real question. Term coverage is usually the cheaper answer when you need temporary protection, while permanent policies are a different animal with a different price tag. Most articles skip this because “it depends” is not clickable enough.
One thing people miss is timing. A 24-year-old with a new baby and a mortgage is in a different universe from a 24-year-old with no debt and a roommate. Same age, totally different need. The calculator has to follow your life, not your birthday.
Comparison What’s Actually Different
|
Option |
What it actually does |
Who it’s for |
The catch |
|---|---|---|---|
|
No policy |
Leaves everything as-is and lets savings, family, or nothing handle the fallout |
Single people with no dependents and little debt |
If you have a co-signer, partner, or private debt, “nothing” can become someone else’s problem |
|
Small term policy |
Covers a set period and pays a fixed amount if you die during that term |
Young adults with debt, co-signers, or dependents who need temporary protection |
It expires, so it is not a forever solution |
|
Bigger term policy |
Replaces more income and covers bigger obligations like a mortgage or children |
Young parents, homeowners, or dual-income households with real obligations |
More coverage costs more, even if term is still fairly affordable |
|
Whole life policy |
Covers you for life and includes a cash value feature |
People who want permanent coverage and can handle higher premiums |
Expensive, harder to justify when your main need is temporary |
For most 18- to 25-year-olds, term life is the sane default if there is a real need at all. Whole life is usually the expensive answer to a question most young adults are not asking yet. That is not anti-whole-life ideology. It is just not pretending every problem needs a permanent product.
What Actually Happens When You Try This
When you actually sit down and calculate it, the number is usually smaller than people fear or larger than they hoped, which is a very rude but useful outcome. The surprise for many young adults is that the biggest issue is not income replacement. It is debt with a human attached to it. A private student loan with a co-signer can matter more than another year or two of salary, and that changes the policy amount fast.
Most people also discover they already have some coverage through work, and it feels nicer than it is. Employer life insurance is fine, but it is often limited, and it usually leaves when the job does. That makes it a convenience, not a real plan. People love treating workplace benefits like a security blanket. Benefits are more like a paper towel.
Another pattern: people overestimate how expensive term insurance is. A healthy 25-year-old can often buy a 20-year, $500,000 term policy for roughly the low tens of dollars per month, with rates varying by health and insurer. That matters because cost anxiety keeps a lot of young adults from even checking. They imagine a bill that feels like car insurance after bad decisions. In practice, the monthly price can be surprisingly manageable.
What nobody warns you about is how quickly your answer changes when your life changes. The version of you at 21 with no debt and no dependents may need almost nothing. The version of you at 25 with a baby, a lease, and a loan may need a very different number. The calculator is not a one-time ritual. It is something you revisit when your life stops being a placeholder.
The Advice Everyone Gives vs What Actually Works
A common piece of advice is “buy 10 times your income.” That rule is useful only as a rough starting point, because it ignores debt, savings, co-signers, and whether anyone depends on you. A better approach is to use that as a ceiling to investigate, not a number to worship. If you have no dependents and minimal debt, 10 times income may be wildly too high.
Another cliché is “get covered as soon as possible.” Sometimes that is true, because younger buyers often get cheaper rates and can lock them in for a term. But “as soon as possible” is not the same as “buy something you do not need.” If there is no financial loss for anyone else, the urgency is mostly marketing.
People also say “always buy term, never whole life.” That is too blunt. Term is usually the practical answer for temporary needs, and whole life can make sense for very specific long-term planning goals. But for most people in their 20s, whole life is a pricey fix for a problem they do not yet have. Start with the need, not the product religion.
Then there is the advice to “just get employer coverage.” That works until you leave the job, get laid off, or discover the policy amount is tiny. Employer coverage is a nice bonus, not a full household plan. Use it as a base layer, not the whole outfit. A single layer is fine until winter shows up.
The grounded version is this: calculate your actual obligation, subtract what you already have, and buy only enough to cover the gap. That is less exciting than a slogan, which is probably why it works.
What To Actually Do
First, write down every debt that could still exist if you died tonight. Be specific. Student loans, car loans, credit cards, and private loans are not the same thing, and a co-signer changes the stakes fast.
Second, check whether any loan is federal or private. Federal student loans are generally discharged at death, while private loans may not be, especially if someone else signed with you. That one detail can save you from buying too much coverage or too little.
Third, look at your existing life insurance through work. If you have one or two times salary, good. That is a start. It is also probably not enough by itself if you have real obligations.
Fourth, decide whether anyone depends on your income right now. A partner, child, or parent who needs your help changes everything. If the answer is no, your need may be tiny.
Fifth, estimate funeral and final expenses. People skip this because it feels grim, but it is one of the few costs that shows up no matter what. A modest policy can keep that from becoming somebody else’s emergency.
Sixth, compare term quotes at the coverage amount you actually need, not the largest number you can tolerate staring at. Rates for young adults can be low enough that the difference between $250,000 and $500,000 is not as dramatic as people expect. Start from need, then price the gap.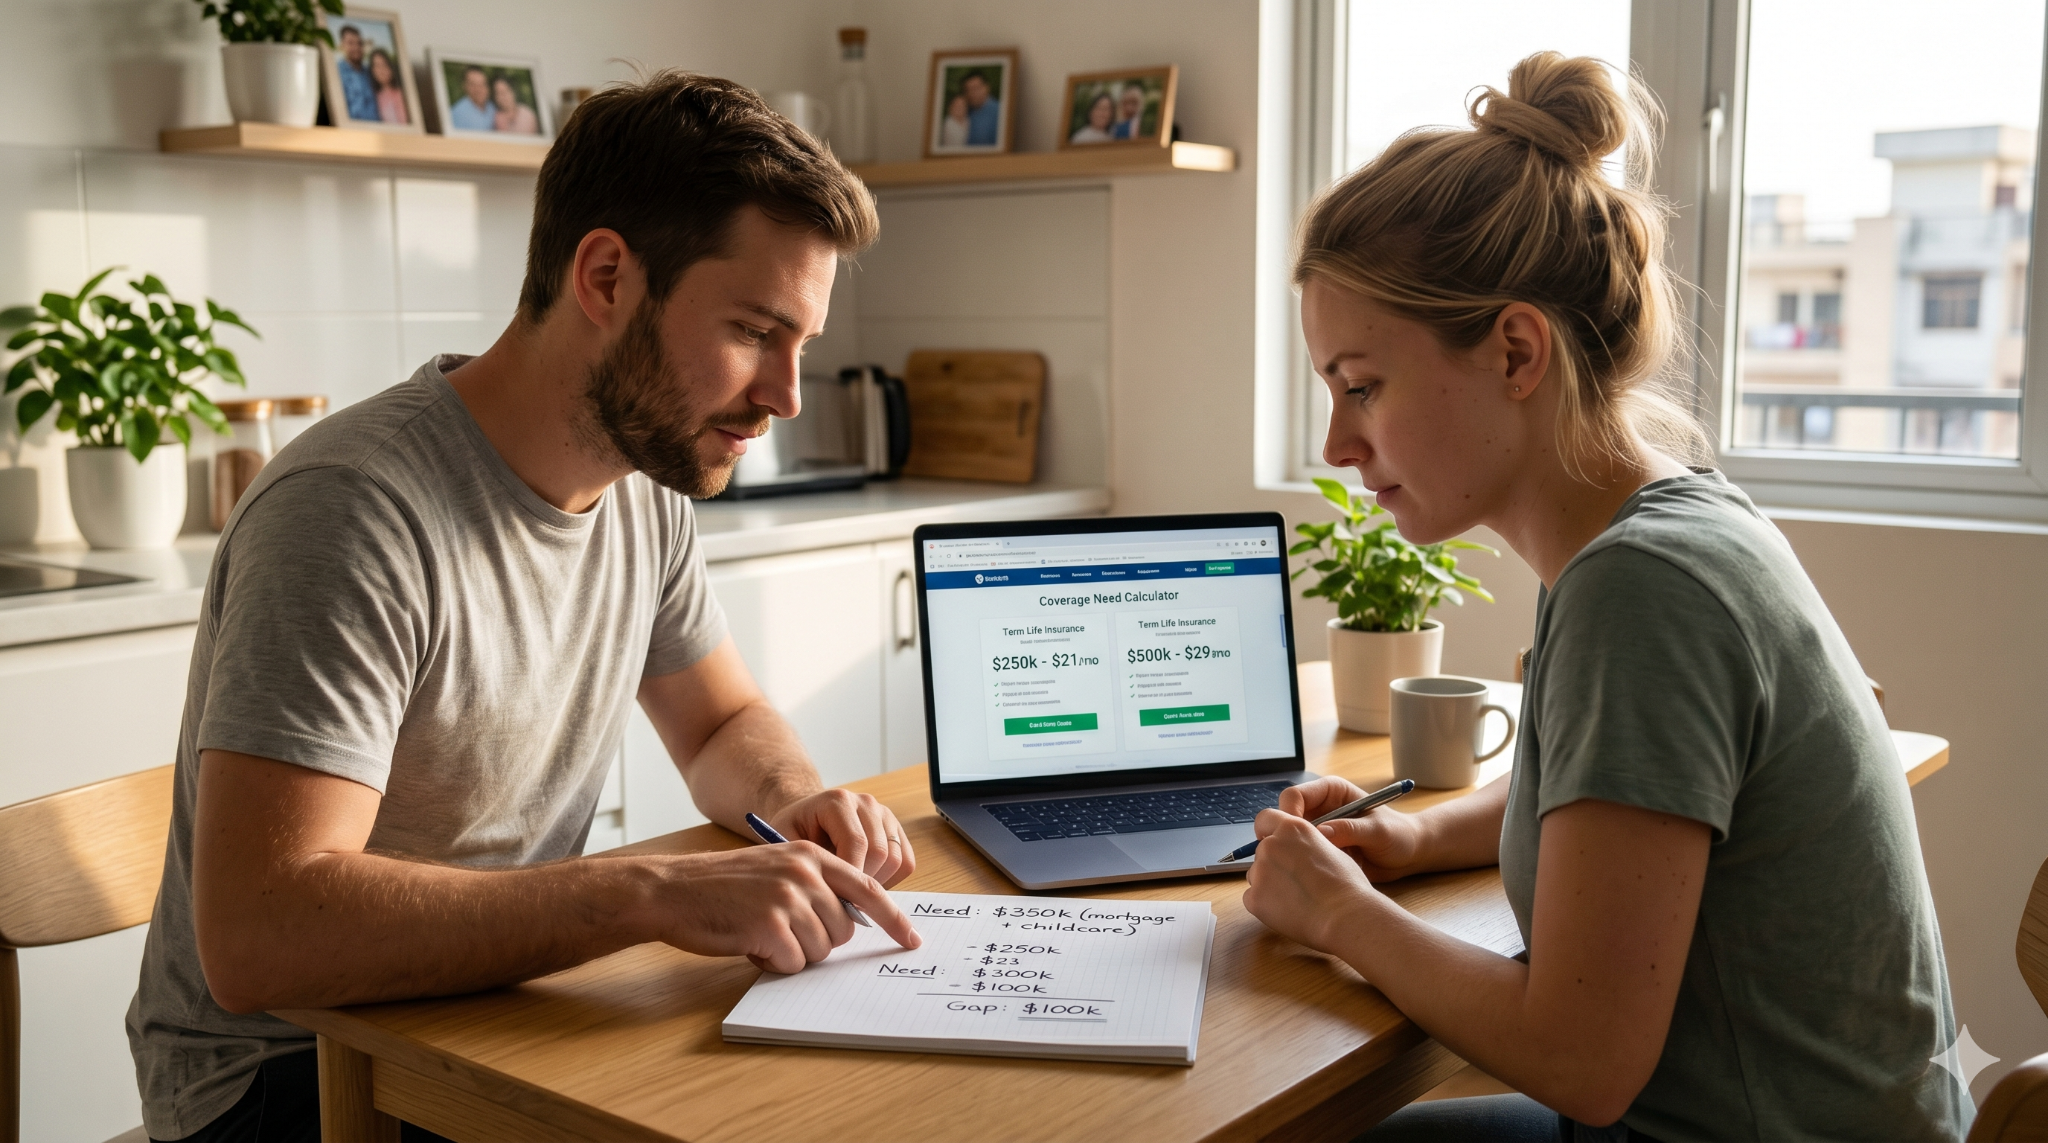
Seventh, set a reminder to revisit the number after life changes. Marriage, a baby, a mortgage, or a new co-signer are all reasons to redo the math. Your life insurance should change when your life does. That is the whole point, irritating as it is.
Also read :- Homeowners Insurance: Covers or Scam?
Questions People Actually Ask
How much life insurance does a 22-year-old need?
A 22-year-old with no dependents and no meaningful debt may need very little or none at all. If there is a co-signed private student loan, a partner relying on your income, or other obligations, the number changes. Start with the gap, not a generic rule.
Is 10 times income too much for a young adult?
Often, yes. The 10-times rule is a rough shortcut, not a law of nature. For a single young adult with no dependents, it can overshoot by a lot.
Should I get life insurance if I have student loans?
Maybe, depending on the type of loan. Federal student loans are generally discharged when the borrower dies, but private loans may remain, especially with a co-signer. That is the part worth checking before you buy anything.
Is employer life insurance enough?
Usually not if you have real financial obligations. Employer coverage is often small and disappears when you leave the job. It is useful, but it is not a full plan.
What is the cheapest way to get covered?
For most healthy young adults, term life is usually the cheapest path for real protection. It covers a set period and avoids the high cost of permanent policies. The tradeoff is that it does not last forever.
How much does $500,000 of life insurance cost at 25?
Rates vary by health, smoking status, and insurer, but a healthy 25-year-old can often get $500,000 of term coverage for a surprisingly modest monthly price. That is one reason young adults are a good fit for term if they actually need coverage. The exact quote depends on your profile.
Do single people need life insurance?
Not always. If nobody depends on your income and you have no co-signed debt, the need may be very small. Single does not mean zero need, but it does mean the calculation is usually simpler.
Should I buy whole life in my 20s?
Usually not as a first move. Whole life is expensive and makes more sense when you have a permanent need and a reason to pay for it. Most young adults are better served by figuring out whether they need temporary protection first.
How often should I recalculate my coverage?
Any time your life changes in a serious way. Marriage, a child, buying a home, or taking on a co-signed loan are the obvious triggers. If nothing changes, once a year is enough.
So Where This Leaves You
The honest answer is that most young adults do not need a giant life insurance policy, and some do not need one at all. The right number is tied to who would be hurt financially, not to how grown-up you feel on a Tuesday. That is the part the glossy explainers tend to skip because it sounds less dramatic than “protect your future.”
If you want a simple move today, do this: list your debts, check for co-signers, and write down any person who depends on your income. That gives you the real starting point. Everything else is noise, which is abundant in this industry.
Conclusion
You made it through the whole thing, which is impressive for a topic that usually gets sold like a motivational poster with a premium. Life insurance is not about buying the biggest number on the screen. It is about buying enough to keep one bad day from becoming someone else’s bill. That is a much less glamorous sentence than the usual marketing copy, but it is the one worth remembering.