You know that tiny panic when a car bill shows up, or your laptop dies, or holiday spending quietly turns into a budget hostage situation. That is the exact problem sinking funds are built to fix. They are not fancy. They are not sexy. They just keep random “big” expenses from wrecking your month.
For US adults in their late teens and early twenties, this matters more than most money advice admits. Your income is still uneven, your expenses keep changing, and every few months life drops a bill on your lap like it had a grudge. A sinking fund gives those costs a place to live before they show up. That is the whole point.
The thing nobody actually says out loud
Most budgeting advice pretends all expenses are either monthly bills or emergencies. Real life does not work like that. Real life has annual insurance premiums, car repairs, birthdays, holiday shopping, class fees, travel, and that one device that breaks at the worst possible time because apparently electronics have a sense of timing.
A sinking fund is just money you set aside little by little for a known future expense. The difference between this and an emergency fund is the label. Emergency funds are for surprises. Sinking funds are for things you already know will happen, even if the date is fuzzy. That distinction sounds small until you realize it keeps you from raiding your safety net for things that were never emergencies in the first place.
The real win is not the savings itself. It is the absence of panic. When the bill comes, the money is already there. No credit card shuffle. No “I’ll pay myself back later,” which is one of the biggest lies people tell themselves with a straight face.
If you have ever watched a streaming show where the characters are always one bad decision away from chaos, sinking funds are the opposite of that energy. They are the budgeting version of having snacks in your bag before the movie starts. Unglamorous. Smart. Very annoying to skip once you understand the pattern.
How this actually works
The mechanics are simple, which is probably why people ignore them and then get surprised later. You list the expenses you know are coming, estimate what they will cost, and divide that number by the number of months you have until the bill arrives. Then you save that amount regularly, usually in a separate account so you are not tempted to spend it on takeout and call it “self-care.”
The niche part generic articles skip is that sinking funds are not just for fun goals like vacations. They work best for the boring stuff that keeps breaking your budget in pieces: car maintenance, phone replacement, annual subscriptions, gifts, school costs, and insurance premiums. That is where the real stress comes from. Not the one big vacation. The random non-monthly expenses that act like they were invited by someone who hates your budget.
A few examples make the math less annoying:
- Car repairs: A $600 repair in six months means saving $100 a month. That is much easier to stomach than pretending the bill will vanish.
- Holiday gifts: A $300 gift budget over ten months means $30 a month. Tiny, yes. But tiny is the point.
- Annual insurance: If your premium is $1,200 a year, setting aside $100 a month keeps it from hitting like a meteor.
- Back-to-school costs: School supplies, fees, and tech expenses add up faster than people expect. A sinking fund keeps them from becoming a “surprise,” which they absolutely are not.
- Travel: If you know a trip is coming, you should save for it in pieces instead of pretending future-you will magically fund it.
- Home or apartment setup: Moving, furniture, and basic repairs show up quickly. A sinking fund makes them feel planned instead of humiliating.
The best way to think about it is this: sinking funds turn unpredictable timing into predictable saving. You still spend the money. You just stop acting shocked when the expense arrives. That alone changes your budget behavior fast.
You can keep sinking funds in a high-yield savings account or even a checking account if the timing is very short and you need easy access. The right choice depends on how soon you will need the money and how tempted you are to move it somewhere else.
Comparison
Here is the part people actually need.
|
Option |
What it actually does |
Who it’s for |
The catch |
|---|---|---|---|
|
Sinking fund |
Saves for a known future expense in small pieces |
People with irregular bills, planned purchases, or recurring big costs |
You have to keep it separate or you will spend it |
|
Emergency fund |
Covers unexpected, urgent problems |
Everyone who wants a safety net |
It should not be used for planned spending |
|
General savings |
Sits there for long-term goals or loose future use |
People saving without a fixed date |
Easy to raid when you are bored, hungry, or both |
My take: if the expense is expected, use a sinking fund. If the expense is a surprise, use an emergency fund. If the money has no job yet, keep it in general savings and stop pretending that counts as a system.
What actually happens when you try this
The first thing that surprises people is how fast the stress drops once the money has a job. A car repair or insurance bill still costs the same amount, but it stops feeling like a personal attack. That is a bigger deal than it sounds like on paper.
When you actually try sinking funds, the hardest part is not the math. It is remembering that the fund exists before the bill arrives. People often do great for three months, then forget the insurance payment is coming and act shocked anyway. That is not a failure of budgeting. It is a failure of memory, which is why automation helps so much.
One pattern that gets missed in a lot of articles is that sinking funds are emotional as much as practical. A fund for “fun things” like travel or gifts makes spending feel guilt-free. A fund for car repairs makes bad weeks feel manageable. A fund for tech replacements means your phone dying is annoying, not catastrophic.
The other thing people do not expect is that sinking funds make budgeting less dramatic. Instead of one giant monthly savings category that means nothing, you get specific buckets with real names and real purpose. That makes it easier to see where your money is going and why.
The advice everyone gives vs what actually works
One common line is, “Just budget better.” That is vague enough to be useless. The better answer is to create separate sinking funds for the things that keep breaking your month, then automate contributions so you do not have to remember every time.
Another popular line is, “Save an emergency fund first.” That is good advice, but it is incomplete. If you keep using your emergency fund for car tires, annual fees, and holiday spending, it will never stay intact long enough to protect you from a real emergency. The realistic fix is to build both systems at once, even if the sinking fund amounts are small.
People also love saying, “Just use a credit card and pay it off later.” Sure. That works until it does not, and then you are paying interest on a problem that was already predictable. A sinking fund is cleaner because it moves the cost earlier, where it belongs.
Then there is the advice to make one giant “miscellaneous” category. That sounds organized until you try to figure out what it actually covers. It usually becomes a dumping ground for everything and nothing. The grounded alternative is to keep separate buckets for the expenses that recur often enough to matter.
My actual opinion is simple: sinking funds are one of the easiest ways to stop living in financial reaction mode. They do not make money magically easier. They just make big expenses less stupid.
The practical part
Start with the expenses that hit you most often. For most people, that means car maintenance, gifts, subscriptions, travel, and yearly fees. Do not build ten funds on day one. Build the ones that keep wrecking your budget first.
Estimate each yearly or one-time cost, then divide by the number of months you have. If your insurance bill is $600 twice a year, that is $100 a month. If your holiday budget is $400, that is about $33 a month. Small numbers work because they are repeatable.
Open a separate place for the money. A separate savings account is usually cleaner than stuffing all of it into checking, because checking money is too easy to spend. Label the account clearly so you do not forget what it is for.
Automate the transfer right after payday. If you wait until the end of the month, the money will mysteriously become unavailable. That is not bad luck. That is how spending works.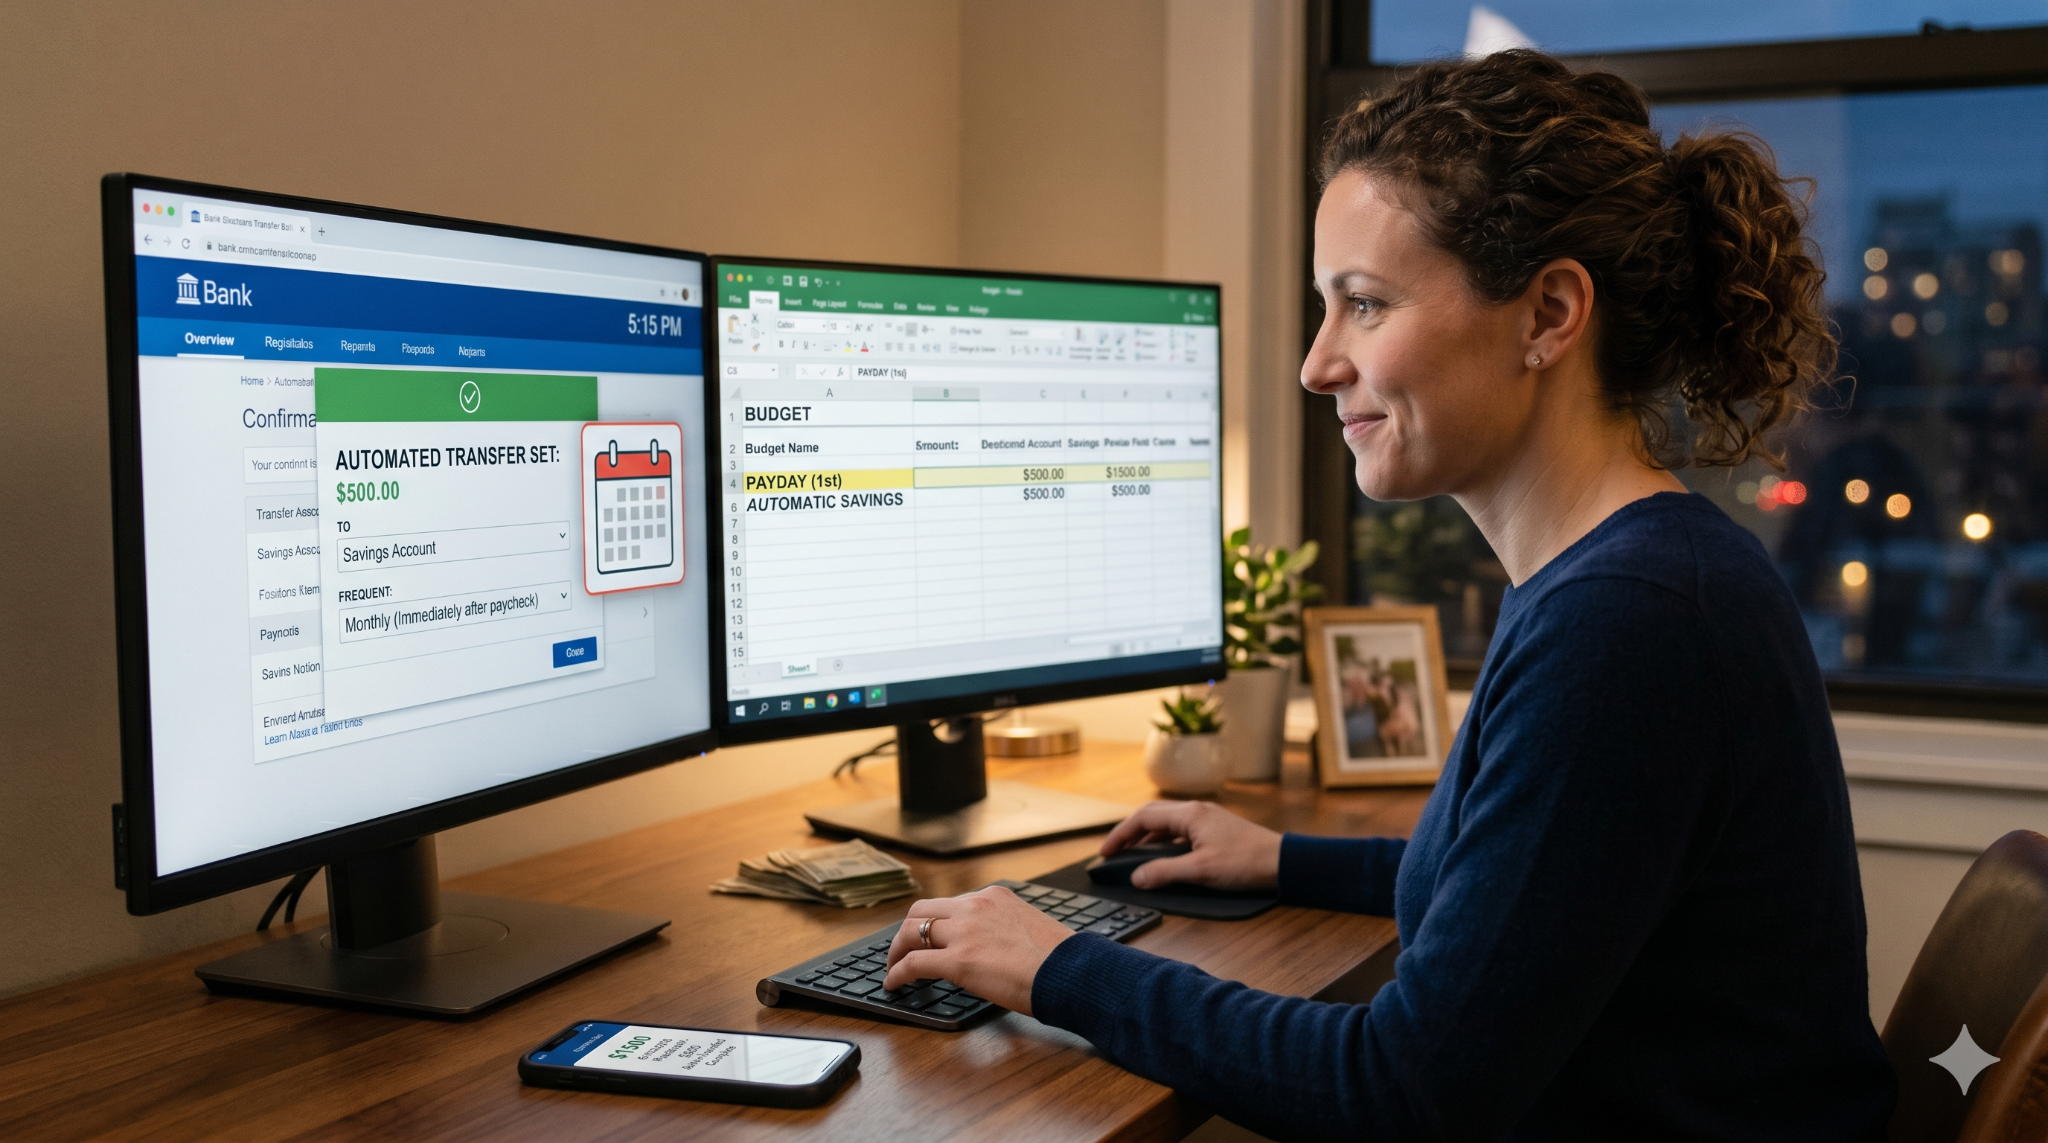
Use sinking funds for things that are predictable, not every possible future event. If the expense is random and urgent, that belongs in your emergency fund. If it has a name and a rough date, it belongs here.
Review the fund amounts every few months. Prices change. Life changes. Your sinking fund should change too. The point is not perfect prediction. The point is staying ahead of the stuff you already know is coming.
Also read:- How to Budget When Your Income Won’t Stay Put
Questions people actually ask
What is a sinking fund in simple words?
It is money you save over time for a bill or purchase you already know is coming. Instead of getting hit with one huge cost, you break it into smaller monthly amounts. That makes big expenses easier to handle.
Is a sinking fund the same as an emergency fund?
No. A sinking fund is for planned expenses, while an emergency fund is for unexpected problems. Mixing them up is how people end up broke when something truly urgent happens.
What should I use a sinking fund for?
Use it for things like car repairs, holiday gifts, travel, annual insurance, school costs, and tech replacements. If you know the expense is coming, it is probably a sinking fund item. That is the whole trick.
Where should I keep my sinking fund money?
Usually in a separate savings account. If the money needs to stay liquid and easy to move, that is the cleanest setup. Some people keep short-term sinking funds in checking, but that makes spending too easy.
How many sinking funds should I have?
Start with three to five. If you try to build fifteen at once, you will probably lose steam and stop. The better move is to cover the expenses that cause the most pain first.
How much should I put into each sinking fund?
Take the cost of the expense and divide it by the number of months until you need it. If your car insurance is $1,200 due in 12 months, that is $100 a month. The math is not glamorous, but it is extremely effective.
Can sinking funds help me avoid credit card debt?
Yes, and that is one of their biggest strengths. If you already saved for the cost, you do not need to charge it and pay interest later. That alone can save a lot of money and stress.
Should I use sinking funds if I have a low income?
Yes, but start small. Even tiny monthly amounts help because they reduce the shock of irregular bills. A $25 or $50 monthly habit is better than waiting until a bill arrives and hoping for the best.
Do sinking funds really work?
Yes, if you actually keep the money separate and keep contributing to it. The method works because it turns big costs into small ones and removes the panic when the bill shows up. The hard part is consistency, not the concept.
So where does this leave you
Sinking funds are not a hack. They are just a better way to handle money you already know you will have to spend. That is why they work so well for people who keep getting blindsided by “surprise” costs that were never really a surprise.
If you want one concrete thing to do today, pick one expense that always annoys you and make a sinking fund for it. Car repairs. Holidays. Annual fees. Pick the one that hurts most, figure out the yearly amount, and start dividing it into monthly chunks.
That is enough to begin. You do not need a perfect budget system to stop getting hit in the face by every big bill. You just need a place for the money before the bill shows up.
Conclusion
If you read this far, you probably already know the problem. It is not that big expenses exist. It is that they keep showing up like they were never invited. Sinking funds fix that without drama.
The line worth keeping is this: money feels a lot less chaotic when every predictable expense has a home. That sounds plain because it is. Plain works.